
If your orders say Yuma, you are not walking into a mystery for us. We are Elite Mortgage, a locally owned mortgage team here in town, and most of the loans we work on are VA loans for families headed to Marine Corps Air Station Yuma or Yuma Proving Ground.
This guide covers the questions we hear before a house-hunting trip: buying before you arrive, BAH, neighborhoods, and the VA loan itself. It is not official military or VA advice, and Elite Mortgage is not affiliated with or endorsed by the VA, the Department of Defense, or the U.S. Marine Corps. We will point you to official sources and tell you what is local and practical. All loans are subject to eligibility, credit approval, and property requirements.
A plain-spoken timeline, from orders to closing
A PCS has its own clock. The loan has another. The work is to line those up so you are not deciding in a rush.
When the orders land
Start with the people whose job is the move, not the mortgage. MCAS Yuma’s Housing Office can walk you through on-base housing, community rentals, and the local market. Housing Referral is at Building 1093 on Thomas Avenue, (928) 269-2826, or Yuma.Housing@usmc.mil. Military OneSource also publishes relocation information. Those offices will not recommend a private lender, and we would not ask them to.
In the same week, look up your BAH on the official DTMO calculator using your duty-station ZIP code, pay grade, and dependency status. We will not quote dollar amounts here. BAH changes by year, ZIP code, and rank.
Then talk with a lender about a pre-approval, not just a pre-qualification. The VA explains the home-buying steps, including the Certificate of Eligibility (COE). Your lender can often request the COE for you. The CFPB is a solid, independent place to review your budget and compare loan estimates.
Buying before you arrive
Plenty of families start the file before they set foot in Yuma. That can work, subject to eligibility and approval, as long as the occupancy plan is honest. A VA-backed loan is for a home you intend to occupy as your primary residence, not a vacation house or a property you plan only to rent out. If a spouse or dependent will be here first, or if you will arrive after closing, we need a timeline that still meets VA rules. Do not sign a contract hoping those details sort themselves out later. See Keeping Your Yuma Home as a Rental When You PCS Again.
The house-hunting trip
Use the trip to stand in the heat, drive the gate at the hour you would actually report, and walk neighborhoods at dusk, not just at noon. Yuma in July does not feel like Yuma in January. The MCAS Yuma Housing Office notes that winter visitors typically swell the population from November through March, and that rental stock is usually wider from April through October.
Work with a real estate professional who understands VA contracts. The VA recommends that the purchase agreement include the VA escape clause if the property does not appraise at the contract price.
Appraisal, inspection, and closing paperwork
A VA appraisal and a home inspection are not the same thing. The appraiser gives an opinion of value and checks minimum property requirements. An inspector looks more closely at the systems, the roof, and what you will live with in the heat. We encourage an inspection even when the appraisal comes back clean.
At least three business days before closing, your lender must give you a Closing Disclosure. Read it. The CFPB has plain-language help for that form. If a number is unclear, ask before you sign.
Power of attorney and signing from somewhere else
PCS life is messy. One of you may still be at the old duty station when the signing date arrives. VA lenders can close with a power of attorney, but it has to be done correctly. The VA requires the lender to confirm that the Veteran is alive and, if on active duty, not missing in action, and to keep a POA (“live and well”) certification.
Title companies and Arizona notary rules also apply. Some families use a mobile notary; others use a properly prepared power of attorney. Whether a fully remote online closing is available depends on the title company and current Arizona requirements. Start that conversation early.
After closing
Then you move in, or your spouse or dependent does, on a timeline that matches the occupancy certification you signed. If later orders take you away from Yuma, selling or keeping the house as a rental is a separate decision. See Keeping Your Yuma Home as a Rental When You PCS Again and Using Your VA Loan a Second Time.
Yuma neighborhoods and the commute to MCAS Yuma and YPG
We will not invent drive times. Traffic, winter visitors, and the gate all change the clock. The figures below come from official pages. Run the route yourself at the hour you would actually drive it.
The air station’s main gate is on Avenue 3E, Yuma, AZ 85365. The MCAS Yuma Community Rentals page describes some mid-town west neighborhoods as about a 15-minute drive to the base, puts Somerton seven miles from the base on Highway 95, describes Ocotillo as five miles east of the base, and puts the Foothills about 12 to 15 miles out. That same official page notes that the Foothills have no apartment complexes and no schools in that area itself. School questions belong with the MCAS Yuma School Liaison, at (928) 269-5373.
Yuma Proving Ground sits approximately 24 miles north of the city of Yuma. Military OneSource also states that YPG is approximately 17 miles from the Foothills (Fortuna Road) and 24 miles from town, with no public transportation on the installation. A house that is convenient to the air station is not automatically convenient to YPG.
For the area-by-area map, see MCAS Yuma and YPG Commute and Neighborhood Guide. On-base or privatized housing starts with the Housing Office and Liberty Military Housing, not with us. We finance off-base purchases.
Climate and utilities: what Yuma is actually like
Yuma is a desert town with a serious summer. The Yuma visitors bureau, citing the National Climate Data Center, describes the area as among the sunniest in the country, with sunshine about 91 percent of possible daylight hours, about three inches of rain a year, and a July average high of 106°F. Those are climate figures, not a forecast. Check the National Weather Service for current conditions.
Cooling is not optional here. Shade, a sound roof, and working air conditioning matter. Arizona Public Service (APS) provides electricity in much of the Yuma area. Water, sewer, and trash providers vary by neighborhood. We will not quote typical bills. Ask which utilities serve the address, and budget honestly for summer cooling.
Winter is milder, visitors arrive, and the rental market tightens, as the Housing Office describes. If you report between November and March, give yourself more time or have temporary lodging. Inns of the Corps handles arrival lodging on the air station side.
BAH, explained without the dollar figures
Basic Allowance for Housing is a military allowance based on your duty station, pay grade, and whether you have dependents. If government housing is not provided, you may be eligible for BAH. That is a Department of Defense program, not a mortgage product. The official lookup is the DTMO BAH Rate Lookup.
BAH is income you can often document for a loan file, subject to lender and VA guidelines. It is not a promise that a particular house will “fit” your allowance, and we will not compare BAH to a housing cost on this page. A loan is approved based on credit, income, debts, residual income, and the property, not on BAH alone. Look up your current rate, then sit down with a budget and a Loan Estimate. The CFPB has independent shopping tools.
VA loan basics for a Yuma PCS
A VA-backed loan is issued by a private lender. The Department of Veterans Affairs guarantees a portion of the loan, which is why many eligible borrowers can buy a primary residence with no down payment, subject to eligibility and approval, and without monthly private mortgage insurance. VA does not lend you the money, does not set your rate, and does not endorse any lender. We are a private mortgage brokerage. We shop your file with wholesale lenders. We are not a government agency.
Entitlement, the funding fee, and the COE
If you have full entitlement, VA does not set a county cap on how much you can borrow. Your practical limit is what you qualify for and what the property appraises for. If entitlement is still charged to another VA loan, county limits come back into the math and a down payment may be required. That is in Using Your VA Loan a Second Time and on VA.gov.
Most VA-backed loans include a one-time funding fee unless you are exempt. As published on VA.gov (rates effective April 7, 2023; page last updated October 5, 2026), a first-use purchase with less than 5 percent down is 2.15 percent of the loan amount; a later use in that situation is 3.3 percent. The fee can usually be paid at closing or rolled into the loan. Borrowers who receive VA disability compensation, and several other official categories, may be exempt. Details are in VA Funding Fee and the Disability Exemption.
The COE is how your lender confirms you have the benefit. You can request it online, or we can request it for you. VA publishes the minimum service requirements. If a discharge or an edge case is involved, we look it up rather than guess.
The VA appraisal and minimum property requirements
Every VA purchase has an appraisal ordered through VA’s system. The appraiser checks value and basic safety, soundness, and sanitation — the minimum property requirements. If the value comes in below the contract price, you may renegotiate, pay the difference if you choose and are able, request a reconsideration of value, or use the escape clause, as VA describes. In Yuma, working cooling and a sound roof are part of whether a house is livable here. An appraisal is still not a home inspection.
Renting versus buying on a two- or three-year tour
We will not tell you that buying is always the smarter move on a short tour. It is not always. Weigh how long you expect to be in Yuma, your overall budget including taxes, insurance, maintenance, and summer utilities if you buy, whether you want the flexibility of a lease (especially in peak visitor season), and the later cost of selling or of keeping the house as a rental. We will not turn that into a comparison against BAH.
The CFPB’s homeownership resources are a solid, independent place to think it through. If you want a local loan conversation, we can walk through VA eligibility and a Loan Estimate. We cannot tell you what the Yuma market will do next year.
If you PCS again, can you keep the Yuma house?
Sometimes, yes — after you have met the occupancy requirement, and if the budget still works. You cannot use a new VA loan to buy a house you intend only as an investment. You may, in many cases, later rent a home you already occupied. Using the benefit again depends on remaining or restored entitlement. See Keeping Your Yuma Home as a Rental When You PCS Again and Using Your VA Loan a Second Time.
Se habla español
Many Yuma households are more comfortable talking through a loan in Spanish. We can do that. The Spanish version of this guide is here: PCS a MCAS Yuma: Comprar una casa con un préstamo VA.
Frequently asked questions
Can I get a VA loan if I have not arrived in Yuma yet?
You may be able to start the file and, in some cases, close before you arrive, subject to eligibility, approval, and a realistic occupancy plan. A spouse or dependent occupying the home can satisfy occupancy in some situations. Confirm the timing before you write an offer, using current VA occupancy guidance.
Do VA loans require a down payment?
VA-backed purchase loans can allow no down payment for eligible borrowers with sufficient entitlement, subject to eligibility and approval, if the contract price does not exceed the appraised value. A down payment may be required if you have only remaining entitlement, if the price is above the appraised value, or if a lender’s own guidelines require one. VA.gov explains the basic structure.
How soon do I have to move in?
You must certify that you intend to occupy the home as your primary residence. Official VA lender training generally treats a “reasonable time” as within 60 days after closing, with limited exceptions for a documented future event (not more than 12 months), spouse or dependent occupancy, deployment, and certain repairs. See the VA loan requirements training. Your lender has to apply the current handbook to your facts.
Can I use a power of attorney if I am still at my old duty station?
Often yes, if the POA meets VA, lender, and Arizona title requirements. VA requires a live-and-well certification when a POA is used. Start early. See VA’s POA certification guidance.
Will sellers take a VA offer in Yuma?
VA offers close regularly in this market. What helps is a real pre-approval, a contract with the VA escape clause, and a lender who answers when the listing agent calls. An appraisal that comes in low is a negotiation, not an automatic failure.
Should I rent first and buy later?
Sometimes that is the calmer path, especially if you arrive in winter or are still learning the commute. Sometimes buying first makes sense if you already know the area and the budget works. We can help with the loan side. There is not one right answer for every tour.
Can I use my VA benefit if I already have a VA loan somewhere else?
Possibly, if you have enough remaining entitlement or if entitlement can be restored, and if you still meet occupancy, credit, and income rules. A down payment may be required. Read Using Your VA Loan a Second Time and the VA entitlement page.
Do you speak Spanish, and can I visit the office?
Yes. Call (928) 597-8122, or come by 1874 S Ave B, Yuma, Monday through Saturday, 9:00 a.m. to 5:00 p.m.
About us: meet your local broker
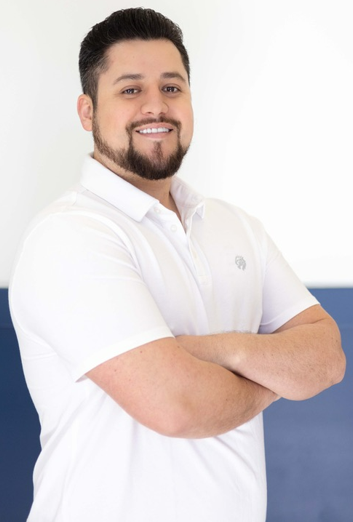
We are Elite Mortgage, a locally owned mortgage team in Yuma. Gustavo Espindola (NMLS #1469643) is the broker most families meet when they call or come to 1874 S Ave B. A large share of the loans we work on are VA loans for households headed to MCAS Yuma or Yuma Proving Ground. We speak Spanish, and we would rather talk through eligibility in plain language before you are under contract.
Talk with a local VA team
If you want a straightforward look at eligibility, a COE, and a Loan Estimate for a Yuma purchase, call us at (928) 597-8122 or visit 1874 S Ave B. We would rather answer occupancy and entitlement questions early than after you are already under contract. There is no obligation, and nothing here is a guarantee of approval.
Ready to use your VA benefit?
Share a few details and we will follow up with your options. No credit check to start, and no obligation.